Numerical investigations
Experiments with Schemes for Exponential Decay
Hans Petter Langtangen
Simula Research Laboratory
University of Oslo
August 20, 2012
Summary. This report investigates the accuracy of three
finite difference schemes for the ordinary differential equation
u'=-au with the aid of numerical experiments. Numerical
artifacts are in particular demonstrated.
Mathematical problem
We address the initial-value problem
$$
\begin{align}
u'(t) &= -au(t), \quad t \in (0,T], \label{ode}\\
u(0) &= I, \label{initial:value}
\end{align}
$$
where \( a \), \( I \), and \( T \) are prescribed parameters,
and \( u(t) \) is the unknown function to be estimated.
This mathematical model is relevant for physical phenomena
featuring exponential decay in time.
Numerical solution method
We introduce a mesh in time with points
\( 0= t_0< t_1 \cdots < t_N=T \).
For simplicity, we assume constant spacing \( \Delta t \)
between the mesh points: \( \Delta t = t_{n}-t_{n-1} \),
\( n=1,\ldots,N \). Let \( u^n \) be the numerical approximation
to the exact solution at \( t_n \).
The \( \theta \)-rule is used to solve \eqref{ode} numerically:
$$
u^{n+1} = \frac{1 - (1-\theta) a\Delta t}{1 + \theta a\Delta t}u^n,
$$
for \( n=0,1,\ldots,N-1 \). This scheme corresponds to
- The Forward Euler scheme when \( \theta=0 \)
- The Backward Euler scheme when \( \theta=1 \)
- The Crank-Nicolson scheme when \( \theta=1/2 \)
Implementation
The numerical method is implemented in a Python function:
def theta_rule(I, a, T, dt, theta):
    """Solve u'=-a*u, u(0)=I, for t in (0,T] with steps of dt."""
    N = int(round(T/float(dt)))  # no of intervals
    u = zeros(N+1)
    t = linspace(0, T, N+1)

    u[0] = I
    for n in range(0, N):
        u[n+1] = (1 - (1-theta)*a*dt)/(1 + theta*dt*a)*u[n]
    return u, t
Numerical experiments
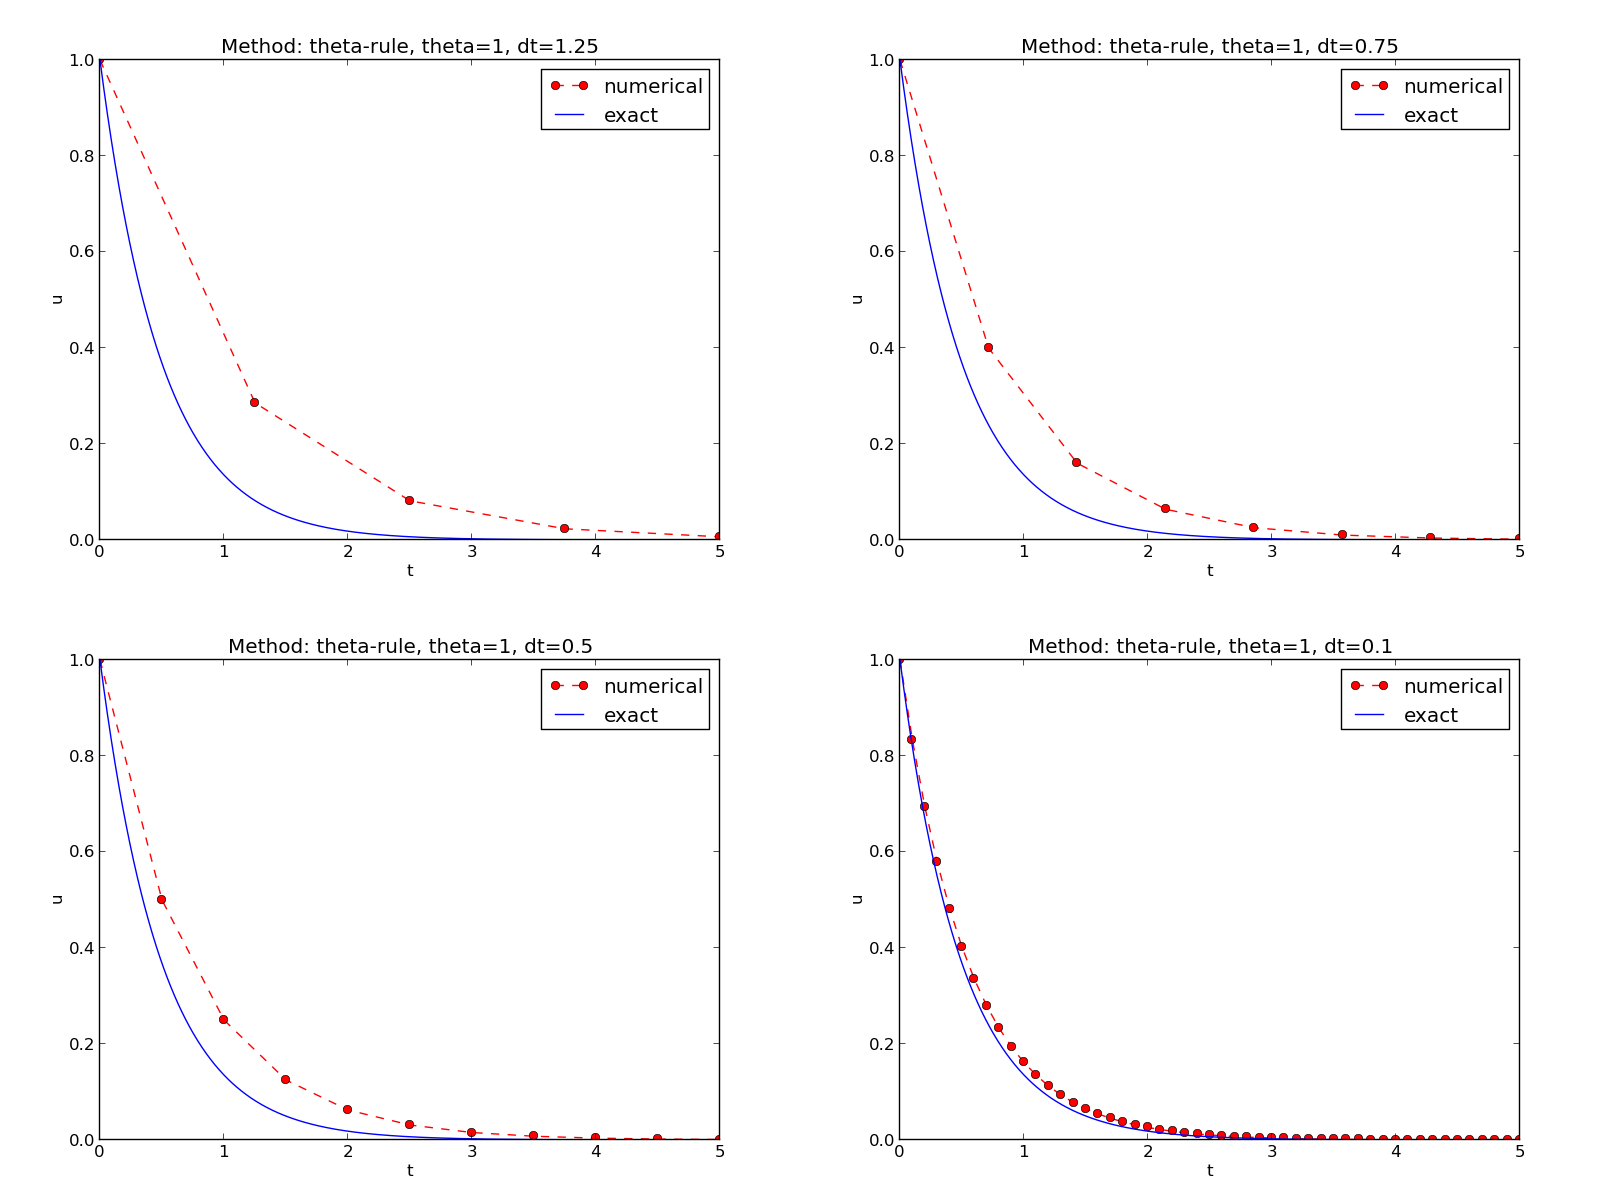
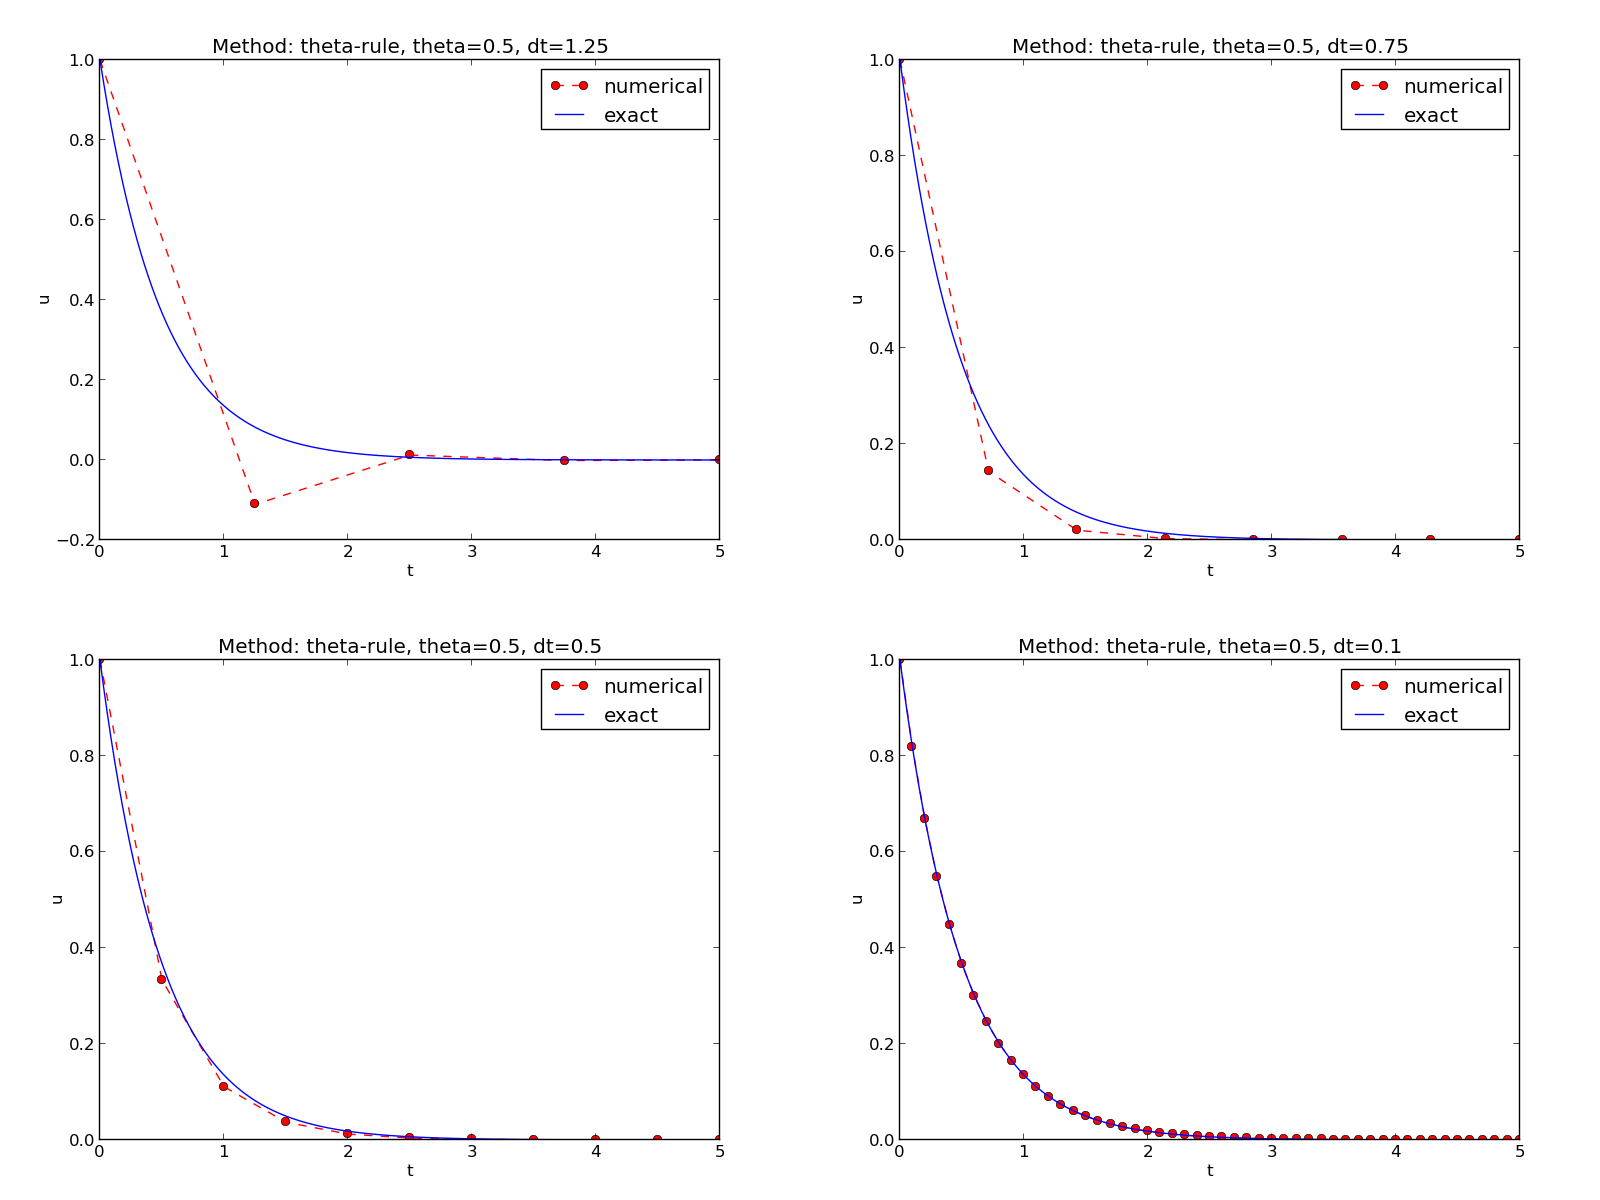
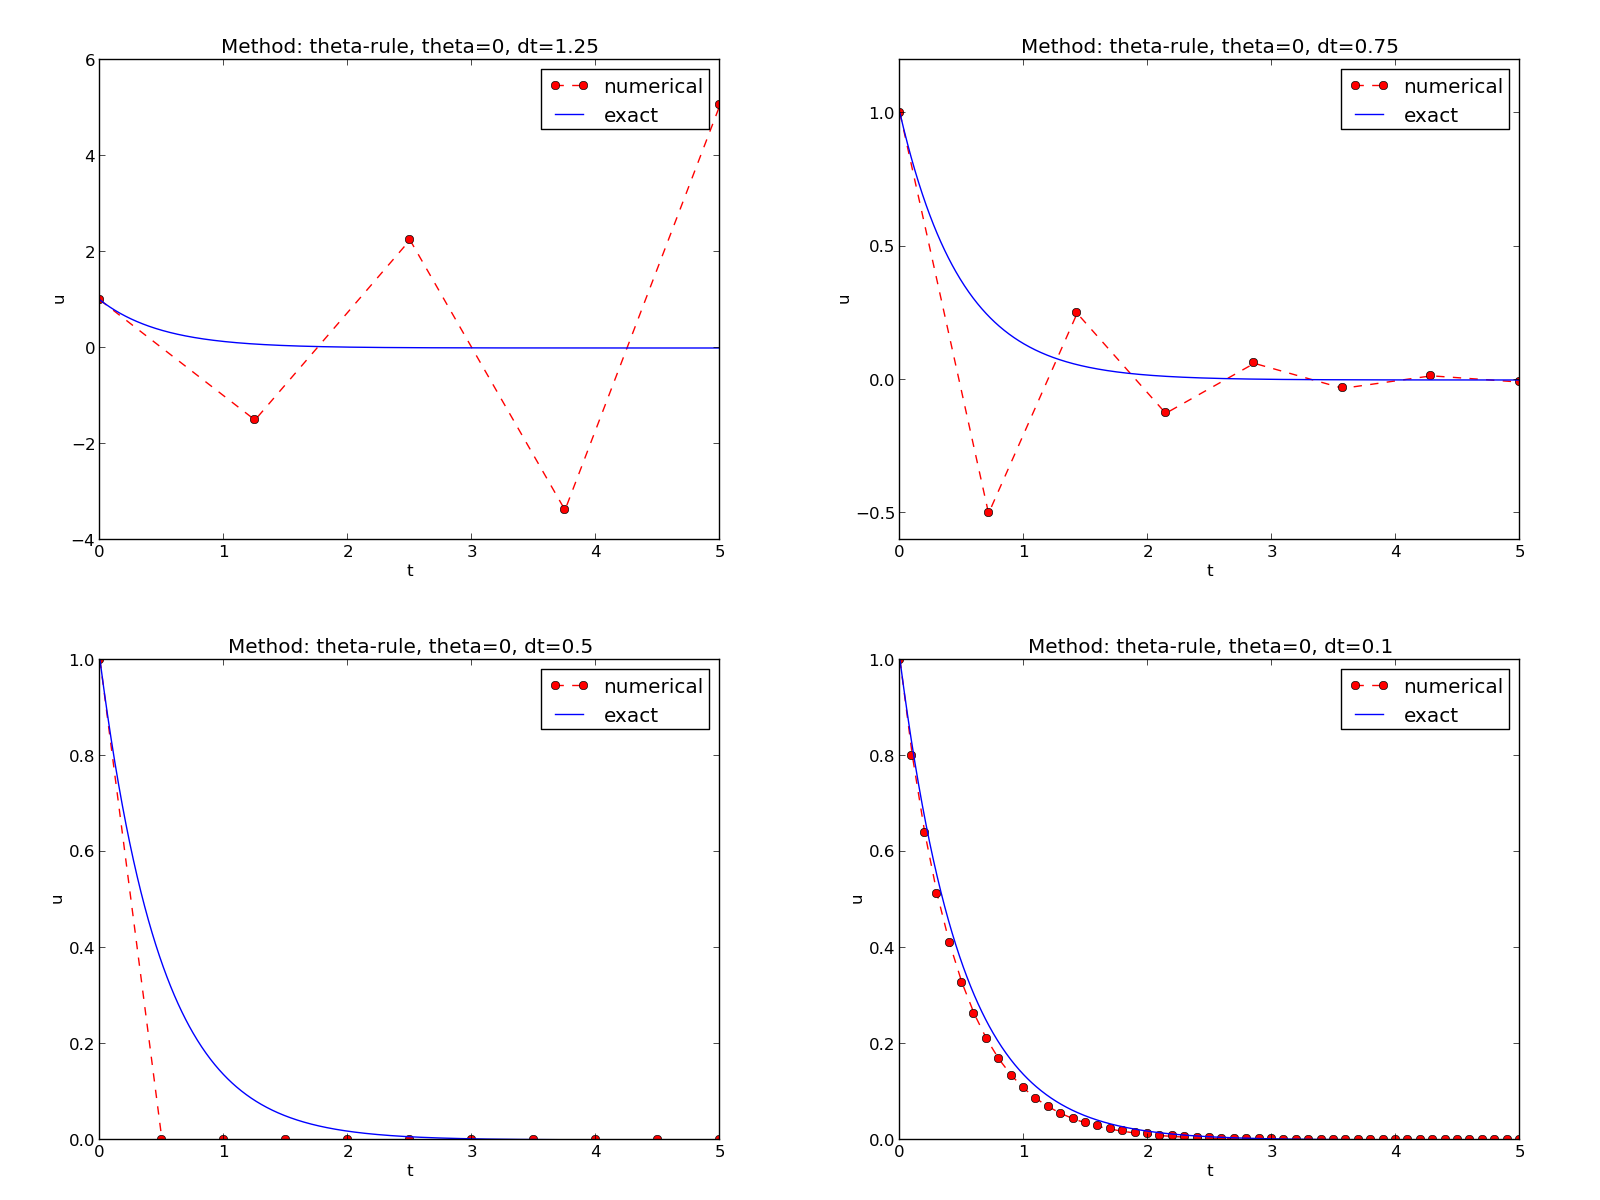
We define a set of numerical experiments where
\( I \), \( a \), and \( T \) are fixed, while
\( \Delta t \) and \( \theta \) are varied.
In particular, \( I=1 \), \( a=2 \),
\( \Delta t= 1.25, 0.75, 0.5, 0.1 \).
The Backward Euler method
The Crank-Nicolson method
The Forward Euler method
Error versus time discretization
How \( E \) varies with \( \Delta t \) for
\( \theta = 0, 0.5, 1 \) is shown below.